Category: Insurance
-

You glance at your auto policy and see two separate lines—collision and comprehensive—each with its own deductible and premium. Many drivers treat them as a single “full coverage” package without knowing what each one actually pays for. Collision and comprehensive protect your vehicle, not other people. Knowing the difference helps you decide whether to keep…
-

You open the renewal notice and the number is higher again. Or you simply feel you are paying more than you should for the coverage you need. Car insurance is required in almost every state, yet the price you pay is not fixed. Small, deliberate changes often produce meaningful savings while leaving your protection intact.…
-
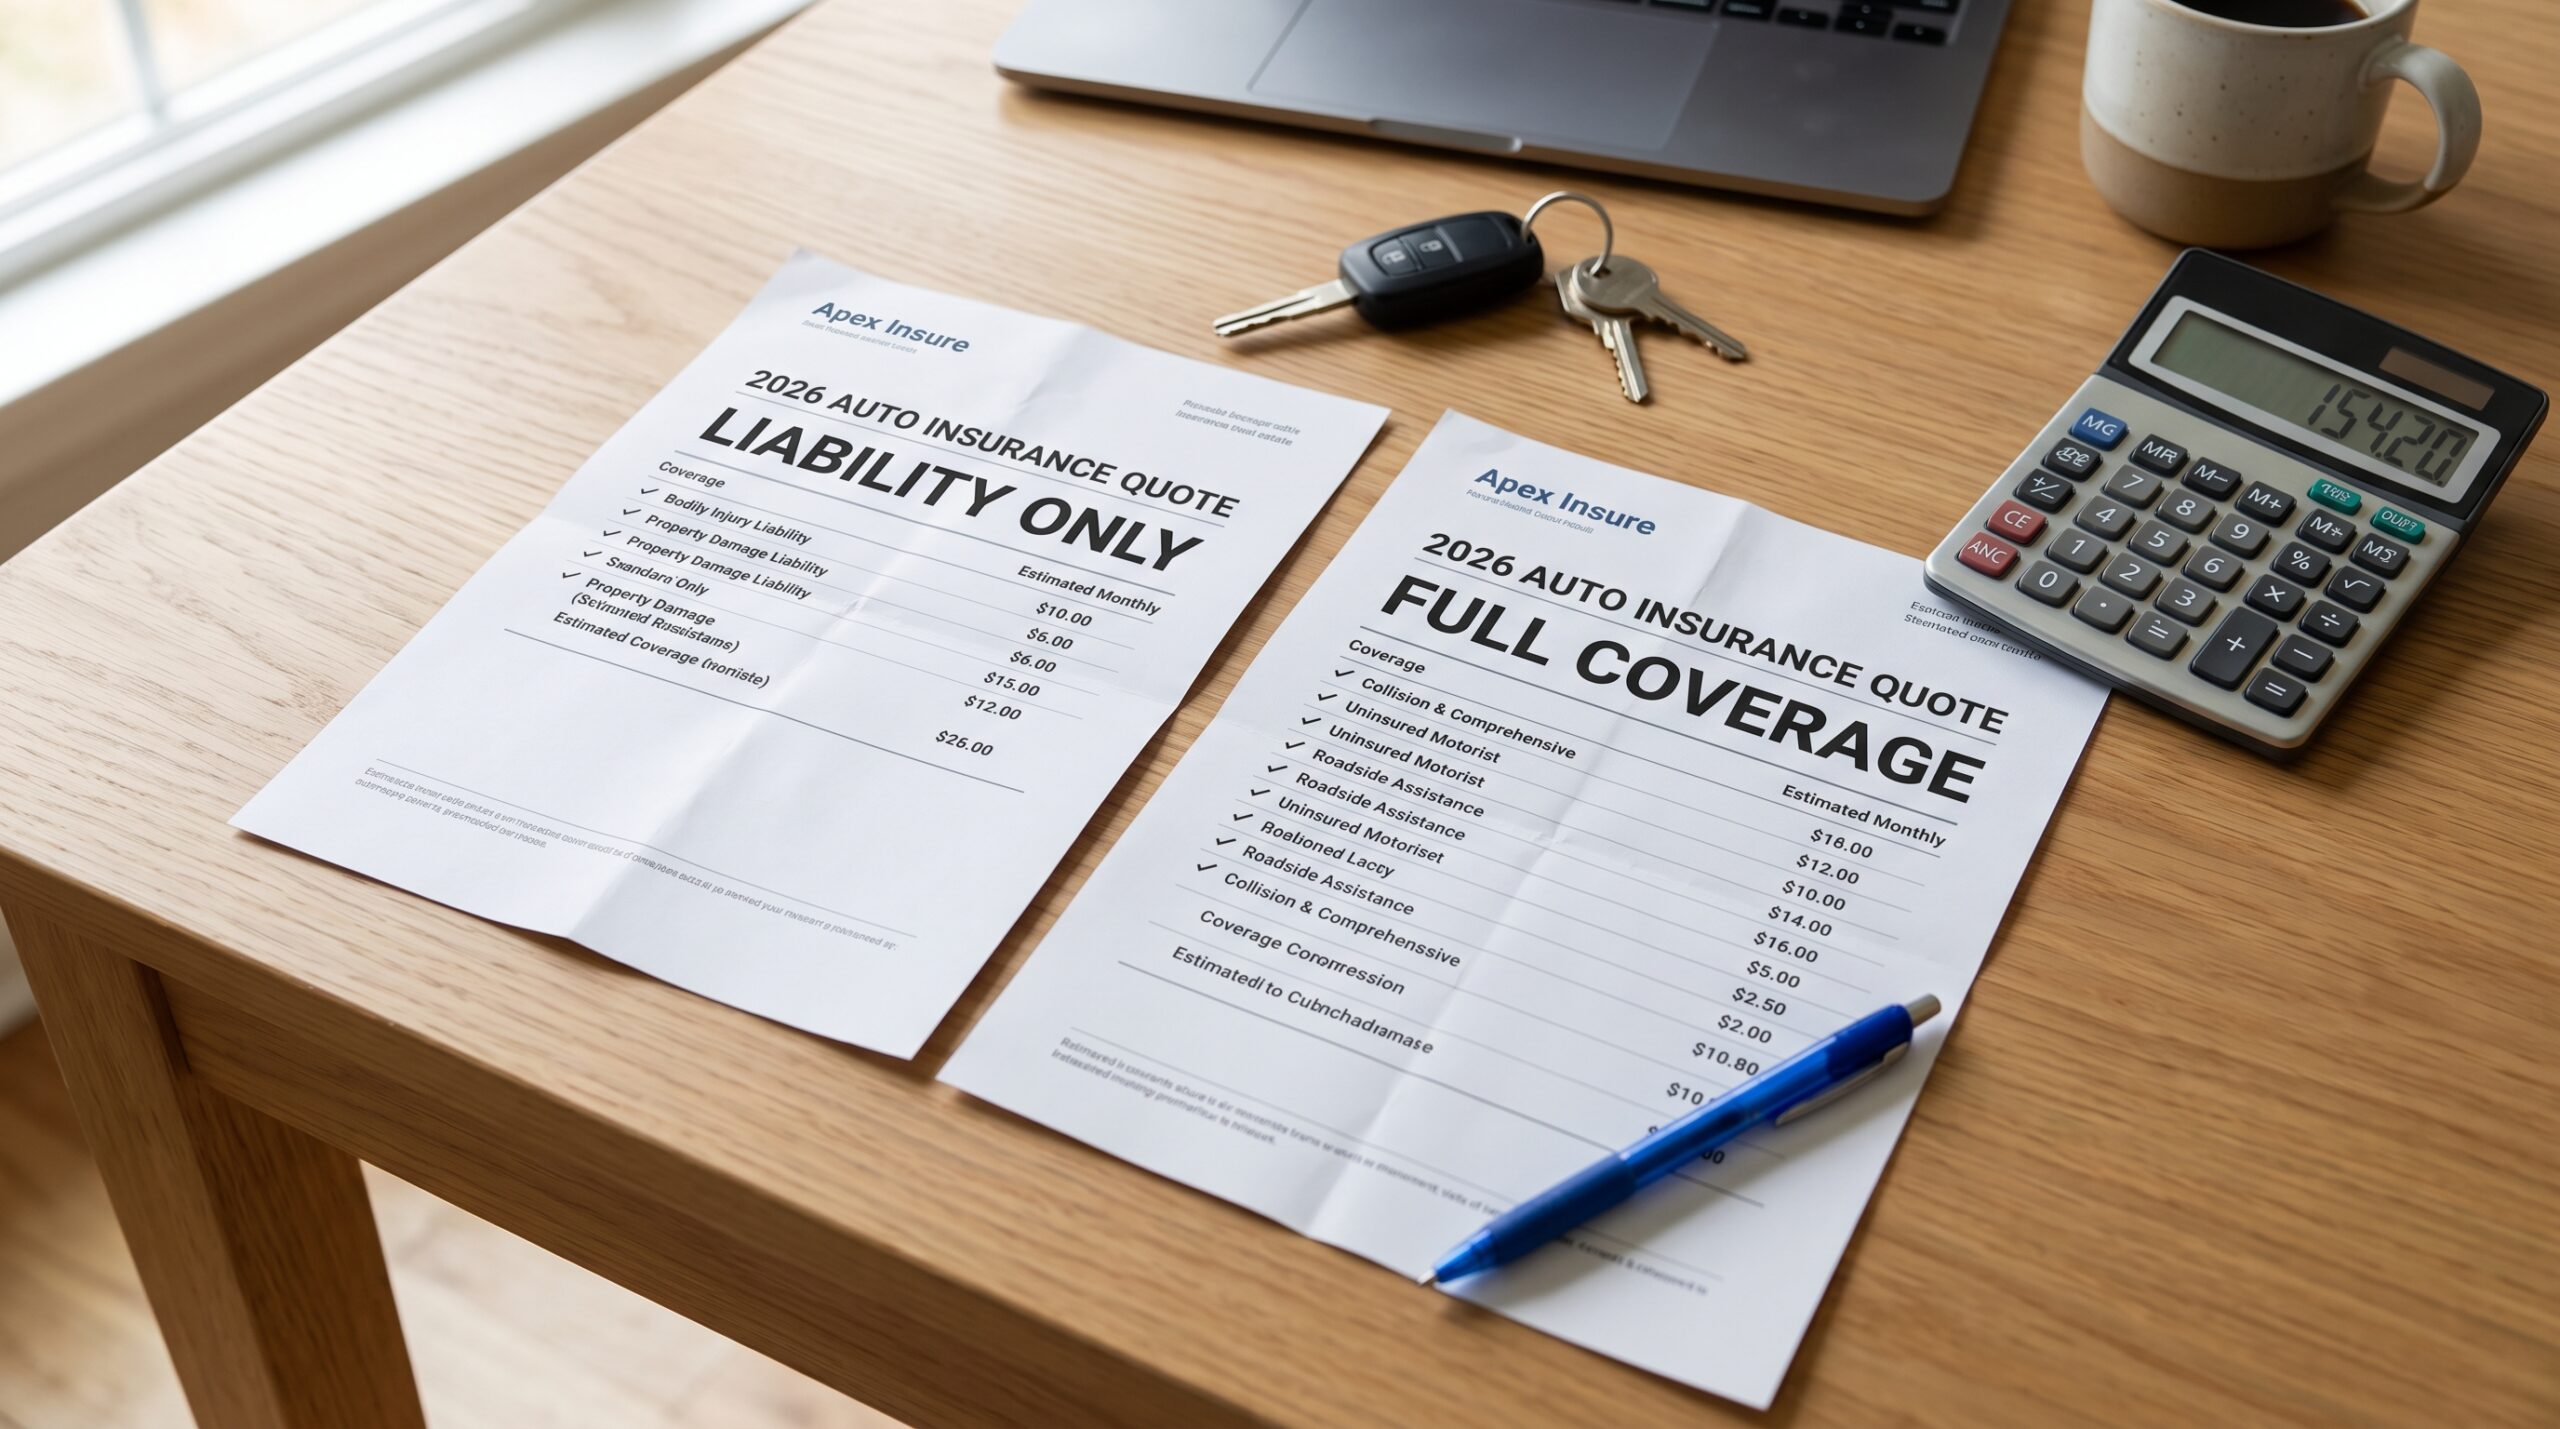
You open an insurance quote and see two very different prices—one for liability-only and one for full coverage—and wonder which you actually need. The gap can be hundreds of dollars a year. The right choice depends on what the law requires, whether your car is financed, how much the vehicle is worth, and how much…
-
Your renewal notice arrives and the premium looks higher than last year. Maybe the home landed on the FAIR Plan after a nonrenewal. Maybe the auto rate climbed even though your driving record stayed clean. Or both policies moved at once and the combined bill feels heavier than it should. California insurance conditions shifted again…
-
You have spent months or years watching private carriers pull back. Non-renewal notices arrived. New quotes became scarce. The FAIR Plan grew into the default option for hundreds of thousands of households. In September 2026 two of the largest names in the market took visible steps in the opposite direction. State Farm General filed updated…
-
You open the renewal notice and the number hits harder than expected. Your California FAIR Plan premium is climbing. For many households the jump lands near or above 29 percent. Some wildfire-exposed homes will see the wildfire portion of the bill roughly double. The change took effect for new and renewing policies on October 15,…
-
You open the renewal and the increase is smaller than last year. In some cases the premium even edges down. After several years of sharp hikes, that feels like relief. National data now show motor vehicle insurance prices running about five percent lower than a year earlier. The long upward march has paused. Do not…
-
You open the renewal notice and the premium is higher again. For the third or fourth year in a row the number climbs, and the explanation feels vague. Across the United States homeowners insurance has reached record levels in 2026, yet the pace of those increases is finally easing. Understanding why costs rose so sharply,…
-
You open the renewal notice and brace for another jump. For the past few years that expectation was usually correct. Double-digit increases became routine. In 2026 the pattern is breaking. Official data now show car insurance prices running about 5 percent lower than a year earlier. The Bureau of Labor Statistics motor vehicle insurance index…
-

You earn solid money, the GKV contribution takes a noticeable bite every month, and the latest reform letters mention higher co-payments plus a raised income ceiling. The question lands hard: should you jump to private health insurance while you still can? The 2027 changes under the GKV-Beitragssatzstabilisierungsgesetz raise the bar for employees who want to…