
You renew your homeowners policy and the number is higher again. Or worse, your carrier non-renews you and the only option left is the FAIR Plan. Across large parts of California that story has become routine. Private insurers have pulled back. The state’s insurer of last resort now carries hundreds of thousands of policies and hundreds of billions in exposure. A fresh 29 percent average rate increase for FAIR Plan dwelling coverage takes effect in mid-October 2026.
Higher premiums are part of the response. They are not a complete solution. The underlying problems run deeper than the price of the last-resort policy. Until those deeper issues are addressed, rate increases will keep arriving and coverage will keep feeling fragile.
The FAIR Plan Was Never Designed for This Scale
The California FAIR Plan exists as a safety net. It was meant to cover properties the voluntary market would not touch, primarily in higher-risk areas. In recent years it has absorbed far more than that original role. Policy counts have more than doubled since 2022. Total exposure has grown even faster. By mid-2026 the plan held roughly 700,000 policies and nearly $770 billion in exposure.
That concentration creates its own risk. When a major wildfire season hits, the financial backstop rests on assessments against the same private insurers that have already reduced their California writings. Rate increases help the plan’s short-term solvency. They do not shrink the book or restore a healthy voluntary market.
Why Private Carriers Stepped Back
Insurers price risk. For years California’s regulatory framework limited their ability to use forward-looking catastrophe models and to fully reflect the cost of reinsurance. Combined with rising rebuild costs, longer fire seasons, and dense development in the wildland-urban interface, the math stopped working for many carriers in many ZIP codes.
Once several large writers restricted new business or non-renewed existing policies, the FAIR Plan became the default for a growing share of homeowners. The crisis then spread. Even some lower-risk suburban and inland areas saw traditional coverage become harder to obtain. Rate hikes on the residual market do not automatically bring those private carriers back.
Rate Increases Treat a Symptom, Not the Cause
The latest FAIR Plan increase averages 29.1 percent statewide. Homeowners in higher wildfire-risk zones will see larger jumps. Some lower-risk policies may even see small decreases. The adjustment improves the plan’s premium-to-exposure ratio on paper. It does not reduce the physical risk of the properties themselves or the concentration of that risk inside one residual market mechanism.
Homeowners feel the higher bills. The structural imbalance remains. As long as the voluntary market stays constrained, more properties will continue flowing into the FAIR Plan, and the cycle of rate pressure will continue.
What Actually Moves the Needle
Three categories of change matter more than another round of residual-market price increases.
First, accurate risk-based pricing in the voluntary market. Allowing carriers to use modern catastrophe models and to reflect reinsurance costs makes it possible for them to write more business at sustainable rates. Recent regulatory adjustments have moved in this direction. The effects will take time to appear in actual availability.
Second, aggressive mitigation that insurers can underwrite. Home hardening, defensible space, and community-level fuel reduction can lower expected losses. When those improvements are verified and recognized in underwriting, some properties can return to the private market. Isolated rate hikes on the FAIR Plan do not create that pathway.
Third, clearer limits and better risk-sharing on the residual market itself. A last-resort mechanism that grows without bound eventually becomes a primary market with concentrated risk. Designing clearer off-ramps and stronger incentives for properties to leave the FAIR Plan once risk is reduced would ease the pressure.
The Human and Economic Cost of Delay
Higher insurance costs feed directly into housing affordability. Buyers and owners in affected areas face larger monthly obligations or gaps in coverage. Mortgage lenders require insurance. When the only available policy is expensive and limited, the friction shows up in real estate transactions and household budgets.
Communities that have invested in mitigation still wait for the insurance market to recognize those investments consistently. The lag between physical risk reduction and insurance relief frustrates homeowners who have done the work.
A More Durable Path Forward
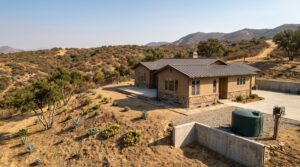
Rate increases will remain necessary when exposure and expected losses rise. They should not be the primary policy tool. Sustainable availability requires a voluntary market that can price risk accurately, a residual market that stays residual, and a serious commitment to reducing physical risk through building standards, land-use decisions, and verified mitigation.
California has begun adjusting the regulatory framework. The next test is whether those changes produce measurable growth in private-market capacity and a gradual reduction in FAIR Plan concentration. Until that happens, another rate filing will not feel like progress to the homeowner opening the renewal notice.
The crisis is real. Higher residual-market premiums are a temporary patch. Fixing the underlying mismatch between risk, regulation, and market capacity is the longer and more necessary work.
FAQ
1. How large is the latest FAIR Plan rate increase?
The approved average increase for dwelling coverage is 29.1 percent, effective for new and renewal business on or after October 15, 2026. Individual changes vary widely by location and wildfire risk.
2. Why have so many homeowners ended up on the FAIR Plan?
Private insurers restricted new policies and non-renewed existing ones in many areas after years of losses, regulatory constraints on pricing, and rising catastrophe risk. The FAIR Plan became the remaining option for a growing number of properties.
3. Will higher FAIR Plan rates bring private insurers back?
Not by themselves. Carriers need the ability to price risk accurately and reflect reinsurance costs before they expand writings again. Rate increases on the residual market do not automatically restore voluntary capacity.
4. Can home hardening help me leave the FAIR Plan?
In some cases yes. Verified mitigation and defensible space improvements are increasingly recognized by certain carriers and can improve the chance of obtaining private coverage, though results vary by insurer and location.
5. Is the insurance crisis limited to high-wildfire zones?
No. Availability problems have spread into some lower- and moderate-risk areas as carriers reduced overall California exposure. The FAIR Plan has grown in places that are not classic wildfire interfaces.
Leave a Reply