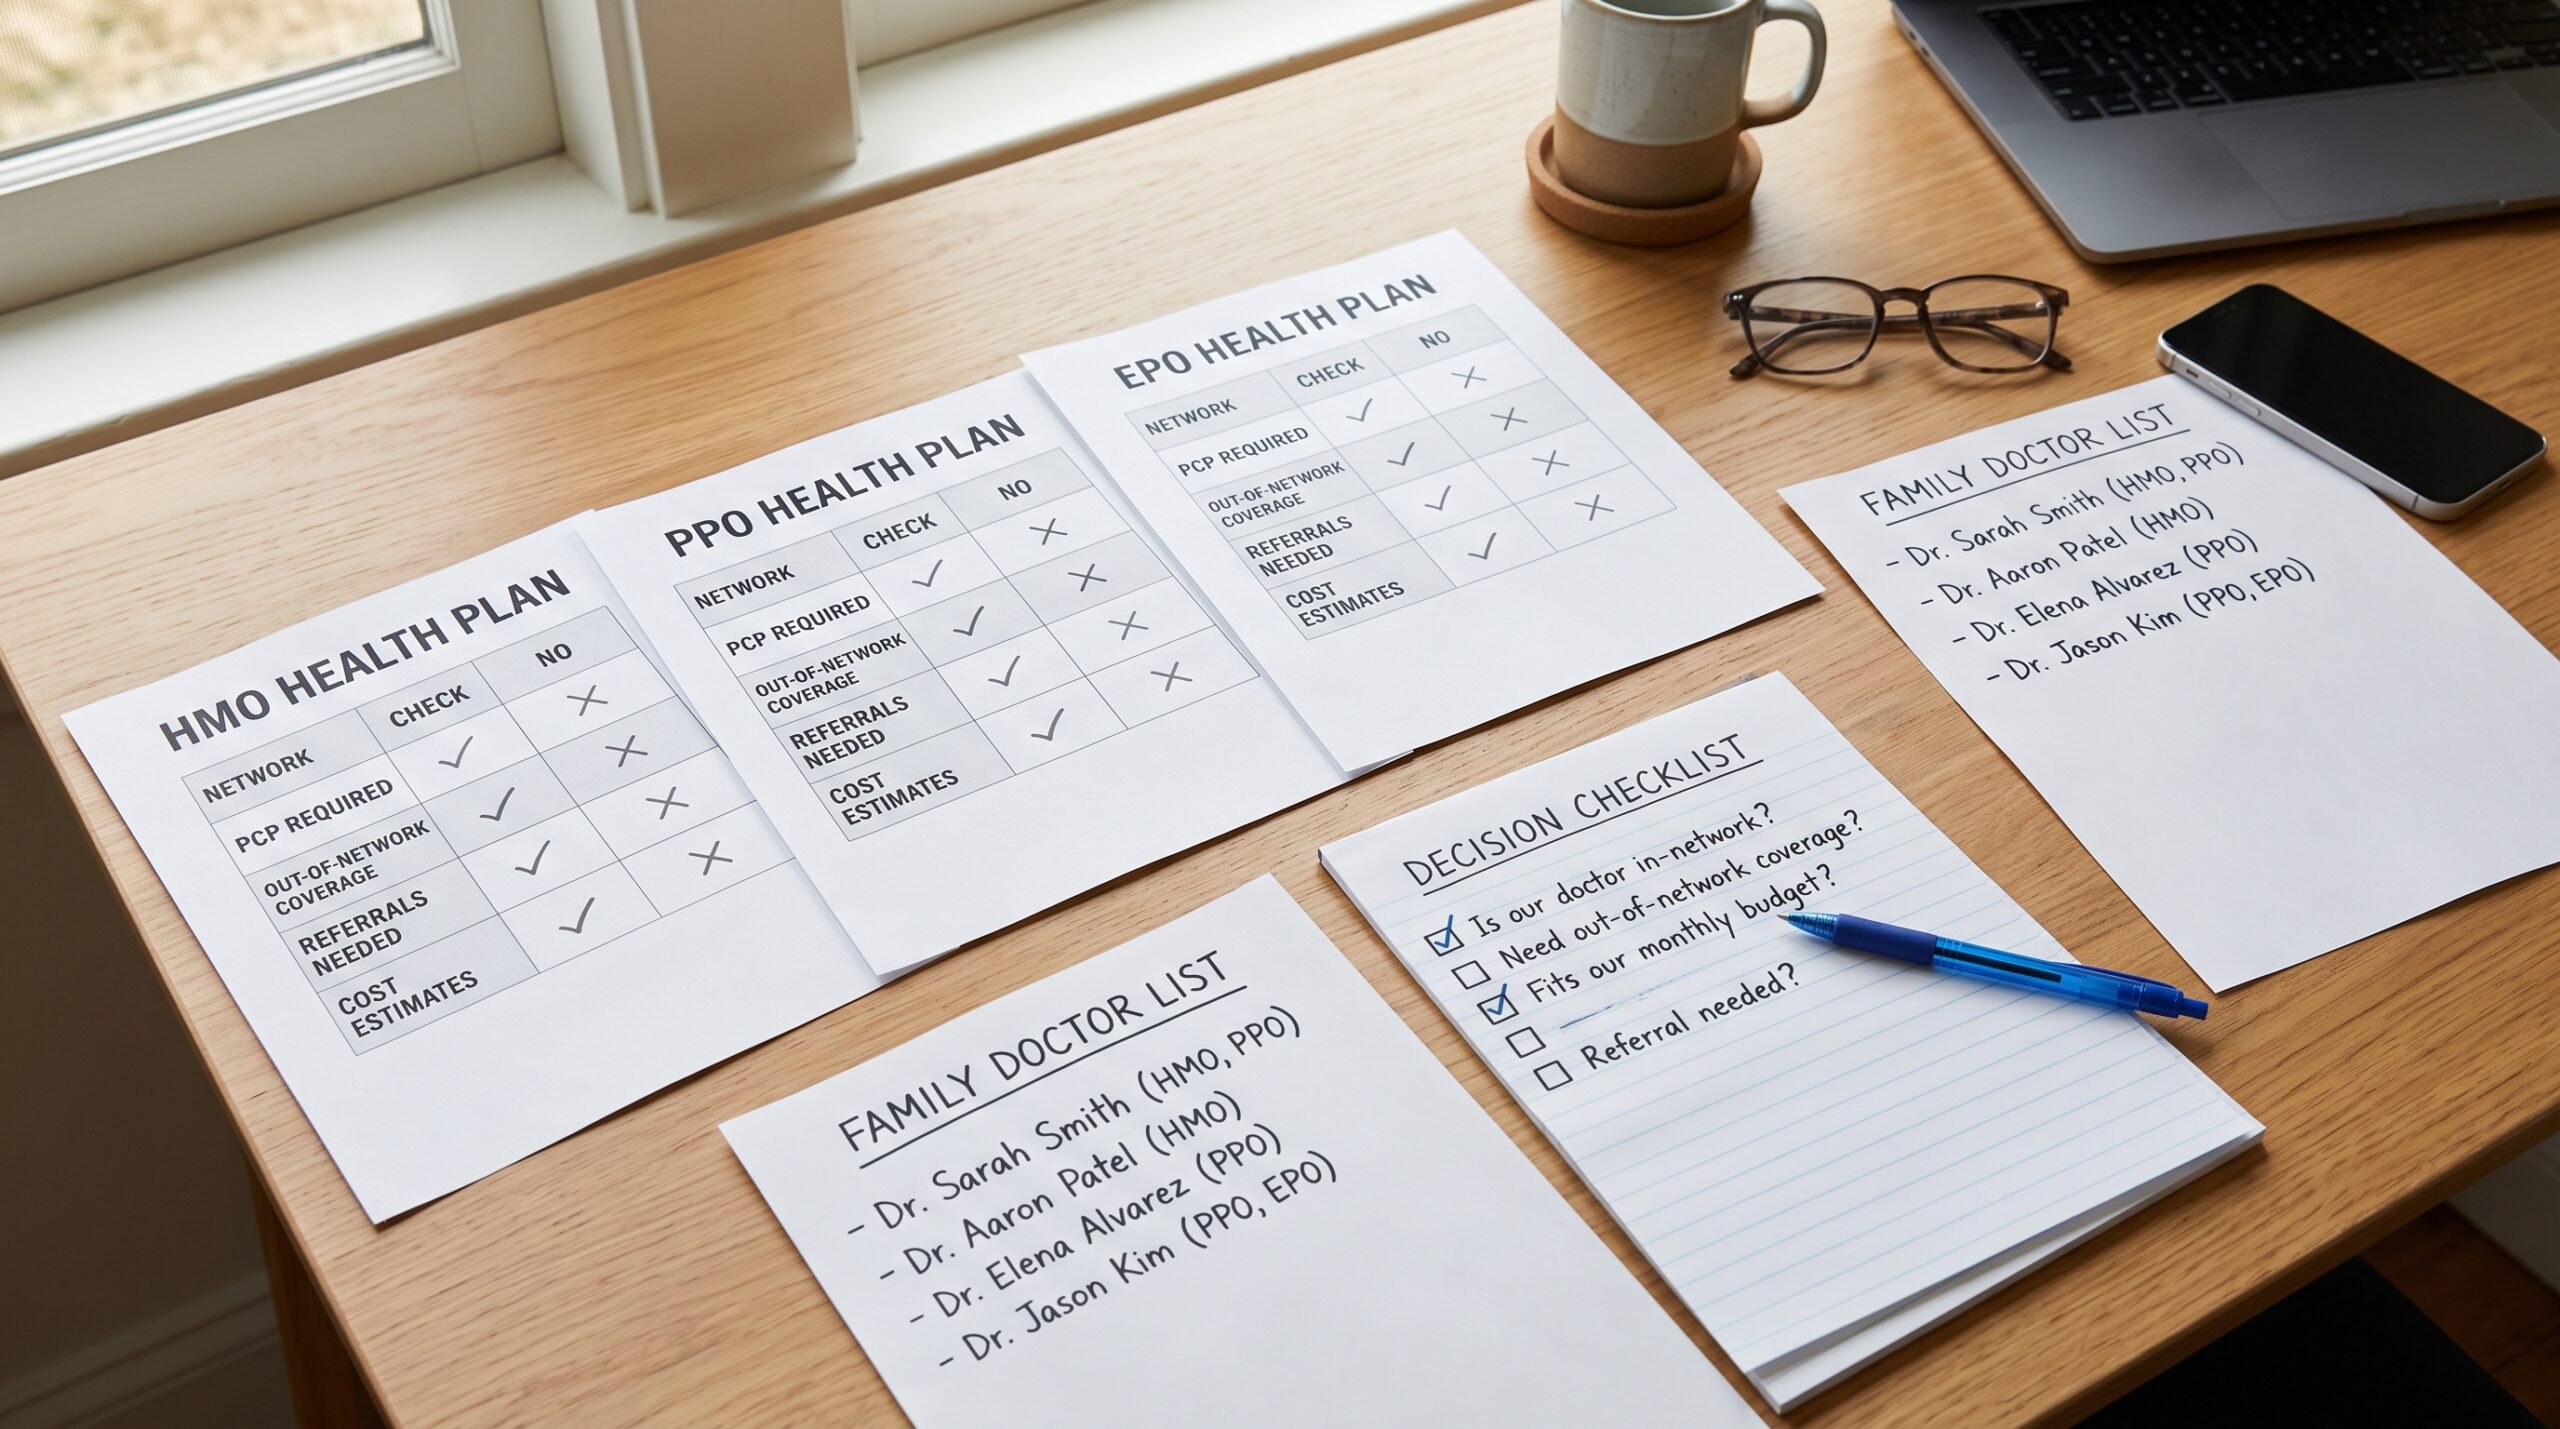
You compare health plans and keep seeing the same three letters—HMO, PPO, EPO—without a clear sense of what they mean for your day-to-day care. The network type decides which doctors and hospitals you can use, whether you need referrals, and how much you pay if you go outside the network. Choosing the wrong structure can lock you into a narrow set of providers or leave you with unexpected bills. A straightforward comparison helps you match the plan style to how your family actually gets care.
What an HMO Requires
A Health Maintenance Organization (HMO) typically requires you to choose a primary care physician who coordinates your care. Specialist visits usually need a referral from that primary doctor. Care is generally covered only when you stay inside the plan’s network, except for true emergencies. Premiums and cost-sharing are often lower than more flexible designs because the network is tighter and care is more managed. If you are comfortable with a gatekeeper model and your preferred doctors are in the network, an HMO can deliver solid coverage at a lower monthly cost.
How a PPO Differs
A Preferred Provider Organization (PPO) gives you more freedom. You can usually see specialists without a referral and may use out-of-network providers, though you will pay more when you do. In-network care costs less; out-of-network care is still covered at a reduced level after higher deductibles or coinsurance. PPOs tend to carry higher premiums because of that flexibility. They suit people who travel, want direct access to specialists, or already have doctors who may not all sit inside a single tight network.
What an EPO Offers
An Exclusive Provider Organization (EPO) sits between the two. Like an HMO, an EPO generally covers care only inside its network (emergencies excepted). Like many PPOs, it often allows you to see specialists without a referral. You get some of the convenience of open access while still facing the network limits of a closed plan. Premiums often fall between pure HMO and PPO levels. An EPO can work well if your doctors are already in the network and you want to avoid referral paperwork without paying for broad out-of-network coverage you may never use.
Key Trade-Offs at a Glance
HMOs emphasize lower cost and coordinated care but limit choice and require referrals. PPOs emphasize choice and direct access but cost more and still reward staying in-network. EPOs limit you to the network like an HMO yet often skip the referral step. No type is universally better. The right fit depends on whether your priority is monthly savings, specialist access, or the ability to see a specific doctor who sits outside narrower networks.
How to Decide Which Fits Your Situation
Start with your current doctors and any specialists you see regularly. If they all participate in a given HMO or EPO network and you are fine getting referrals when needed, the lower premium of a tighter network can make sense. If you need the ability to go out of network or dislike referral requirements, a PPO is usually the more practical choice. Also consider how often you travel or seek care away from home; PPOs handle that more gracefully. Hypothetical illustration: a family whose pediatrician, internist, and main specialists all belong to a local EPO network chooses the EPO for lower premiums and no referrals. Another household with a preferred specialist outside most local networks selects a PPO so that relationship can continue without full out-of-pocket cost.
Other Practical Checks
Even within the same network type, plans differ on deductibles, copays, and out-of-pocket maximums. Always verify the specific provider directory and drug formulary for the plan year you are buying. Networks change. A doctor who accepted the plan last year may not next year. Confirm hospital systems and urgent-care options as well. If you take regular medications, make sure they remain covered at acceptable tiers under the new plan.
Balancing Cost and Flexibility

Lower premiums usually come with tighter rules. Higher premiums usually buy more freedom. Map your expected care for the year—routine visits, specialists, possible procedures—and estimate total cost under each network style, not just the monthly premium. Include the risk of an unexpected out-of-network need if you choose a closed network. The goal is a plan whose rules you can live with and whose total cost you can afford when care is actually used.
HMO, PPO, and EPO describe how a plan organizes its provider network and referral rules. HMOs trade flexibility for lower cost and coordinated care. PPOs trade higher cost for broader choice and fewer gatekeepers. EPOs keep you in-network while often removing referral requirements. Match the structure to your doctors, your need for specialist access, and your tolerance for network limits. Check the actual directory and formulary for the coming year, compare total expected costs, and pick the network type that fits how your household gets care rather than the one that simply looks cheapest on the first page.
FAQ
Do I need a referral to see a specialist in an HMO?
Usually yes. Most HMOs require a referral from your primary care physician for specialist care.
Can I use out-of-network doctors with a PPO?
Yes, though you will typically pay more than for in-network care. Coverage still applies at a reduced level.
What is the main difference between an EPO and an HMO?
Both generally limit coverage to in-network providers, but many EPOs allow specialist visits without a referral.
Which network type is usually cheapest?
HMOs often have the lowest premiums because of tighter networks and managed care. Exact prices vary by plan and location.
Should I choose based only on network type?
No. Also compare deductibles, out-of-pocket maximums, drug coverage, and whether your specific doctors and hospitals are in the network for the plan year.
Leave a Reply