The loan that felt manageable two years ago now eats a wider slice of every deposit. A credit line renewal arrives with a higher rate. Equipment you planned to finance suddenly needs a larger down payment to keep monthly costs in check. Rising interest rates rarely announce themselves with a single crisis. They show up as tighter math on decisions you used to make on instinct.
For small businesses, higher rates raise the cost of borrowing, cool some customer demand, and shift the advantage toward operators with clean cash flow and less floating-rate debt. This article explains the main pressure points and practical responses. It is general business education—not financial, lending, or investment advice. Credit conditions vary by country, bank, and borrower profile.
Why Rate Hikes Hit Smaller Firms Harder
Large corporations often tap bond markets, hold cash buffers, and negotiate from scale. Many small businesses rely on variable-rate lines of credit, term loans tied to prime or other benchmarks, merchant cash advances, and equipment financing. When policy rates rise, those instruments reprice faster than a fixed long-term bond issued years earlier.
Landlords, wholesalers, and contractors may also pass along their own higher financing costs through rent and supplier prices. You feel the squeeze on both sides: more expensive credit and stickier input costs. That combination compresses margins even when sales look “fine” on the surface.
Expert Insight From Main Street Credit Reviews
Banks under higher rates often tighten covenants and preference stronger balance sheets. A profitable shop with messy books can face worse terms than a slightly leaner peer with clear statements and predictable receivables.
Floating Debt and Refinancing Risk
If your loan rate resets with a benchmark, each hike can lift the monthly payment without a single new hire or lease. Refinancing from a low fixed rate into today’s market can mean accepting higher interest to unlock cash or extend term. Some owners postpone refinancing and live with balloon risk later—a different kind of stress.
Map every credit facility: fixed or variable, reset dates, prepayment penalties, and personal guarantee terms. Build a simple schedule of what a 1% or 2% move does to monthly service. Surprise is the expensive part. Arithmetic is manageable when you see it early.
Hypothetical Retail Example
A shop carries a variable line used for inventory before peak season. Rates climb, interest expense rises, and the owner buys thinner inventory batches more often. Sales continue, but stockouts rise and supplier shipping fees add friction. The rate hike did not close the store. It changed operating rhythm.
Customer Demand and Big-Ticket Hesitation
Higher rates affect your customers too. Households and other businesses delay financed purchases—vehicles, renovations, equipment, discretionary upgrades—when monthly payments jump. Service firms tied to those purchases see pipelines stretch. Hospitality and everyday essential retail may hold up better than luxury or highly leveraged B2B projects.
Watch leading indicators in your niche: deposit trends, booking lead times, average order value, and how often quotes die at financing. Adjust staffing and inventory before a soft month becomes a cash crisis. Rate-driven slowdowns often arrive gradually, then all at once in a single slow quarter.
Compact Demand Checkpoint
Which products depend on customer financing? What share of revenue is discretionary? Are B2B clients delaying projects? Can you offer smaller packages or phased work? Do deposits cover a longer sales cycle? Which costs flex within thirty days if bookings dip?
Working Capital, Inventory, and Growth Projects
Elevated rates raise the hurdle for any project funded with debt: a second location, a packaging line, a vehicle, or a software implementation paid over time. Projects with slow payback lose to projects that return cash inside a year. Equity or retained earnings become more attractive relative to borrowed growth when interest is dear.
Inventory is working capital you must finance. In a higher-rate environment, excess stock is not only storage cost—it is capital charged at a higher opportunity rate. Tighten SKUs, negotiate supplier terms, and improve collection speed so you borrow less against receivables.
Expert Insight on “Wait Mode”
Not every delayed expansion is fear. Sometimes waiting is rational until fixed-rate options, vendor financing, or internal cash improve the deal. The mistake is drifting without a number: decide what rate or cash threshold restarts the project.
Practical Moves Operators Are Using
Refinance only with a full comparison of total interest, fees, and term—not a lower payment that extends debt deeper into the future. Where possible, convert chaotic short-term balances into structured schedules you can plan around. Cut nonessential subscriptions and idle equipment leases that effectively carry financing costs.
Strengthen banking relationships before you need emergency credit. Updated financials, tax returns, and a clear use-of-proceeds story improve outcomes when underwriting is selective. Consider invoice factoring or supplier terms carefully; compare their true annualized cost to bank rates so “easy cash” does not become the most expensive line on the P&L.
Hypothetical Service Business
A trades company pauses a truck purchase, renegotiates a supplier discount for faster payment, and moves two slow-paying clients to stricter terms. Cash on hand rises enough to fund a smaller equipment buy without new debt. Rate pressure forced discipline that growth years had postponed.
Cash Flow Discipline Becomes the Strategy
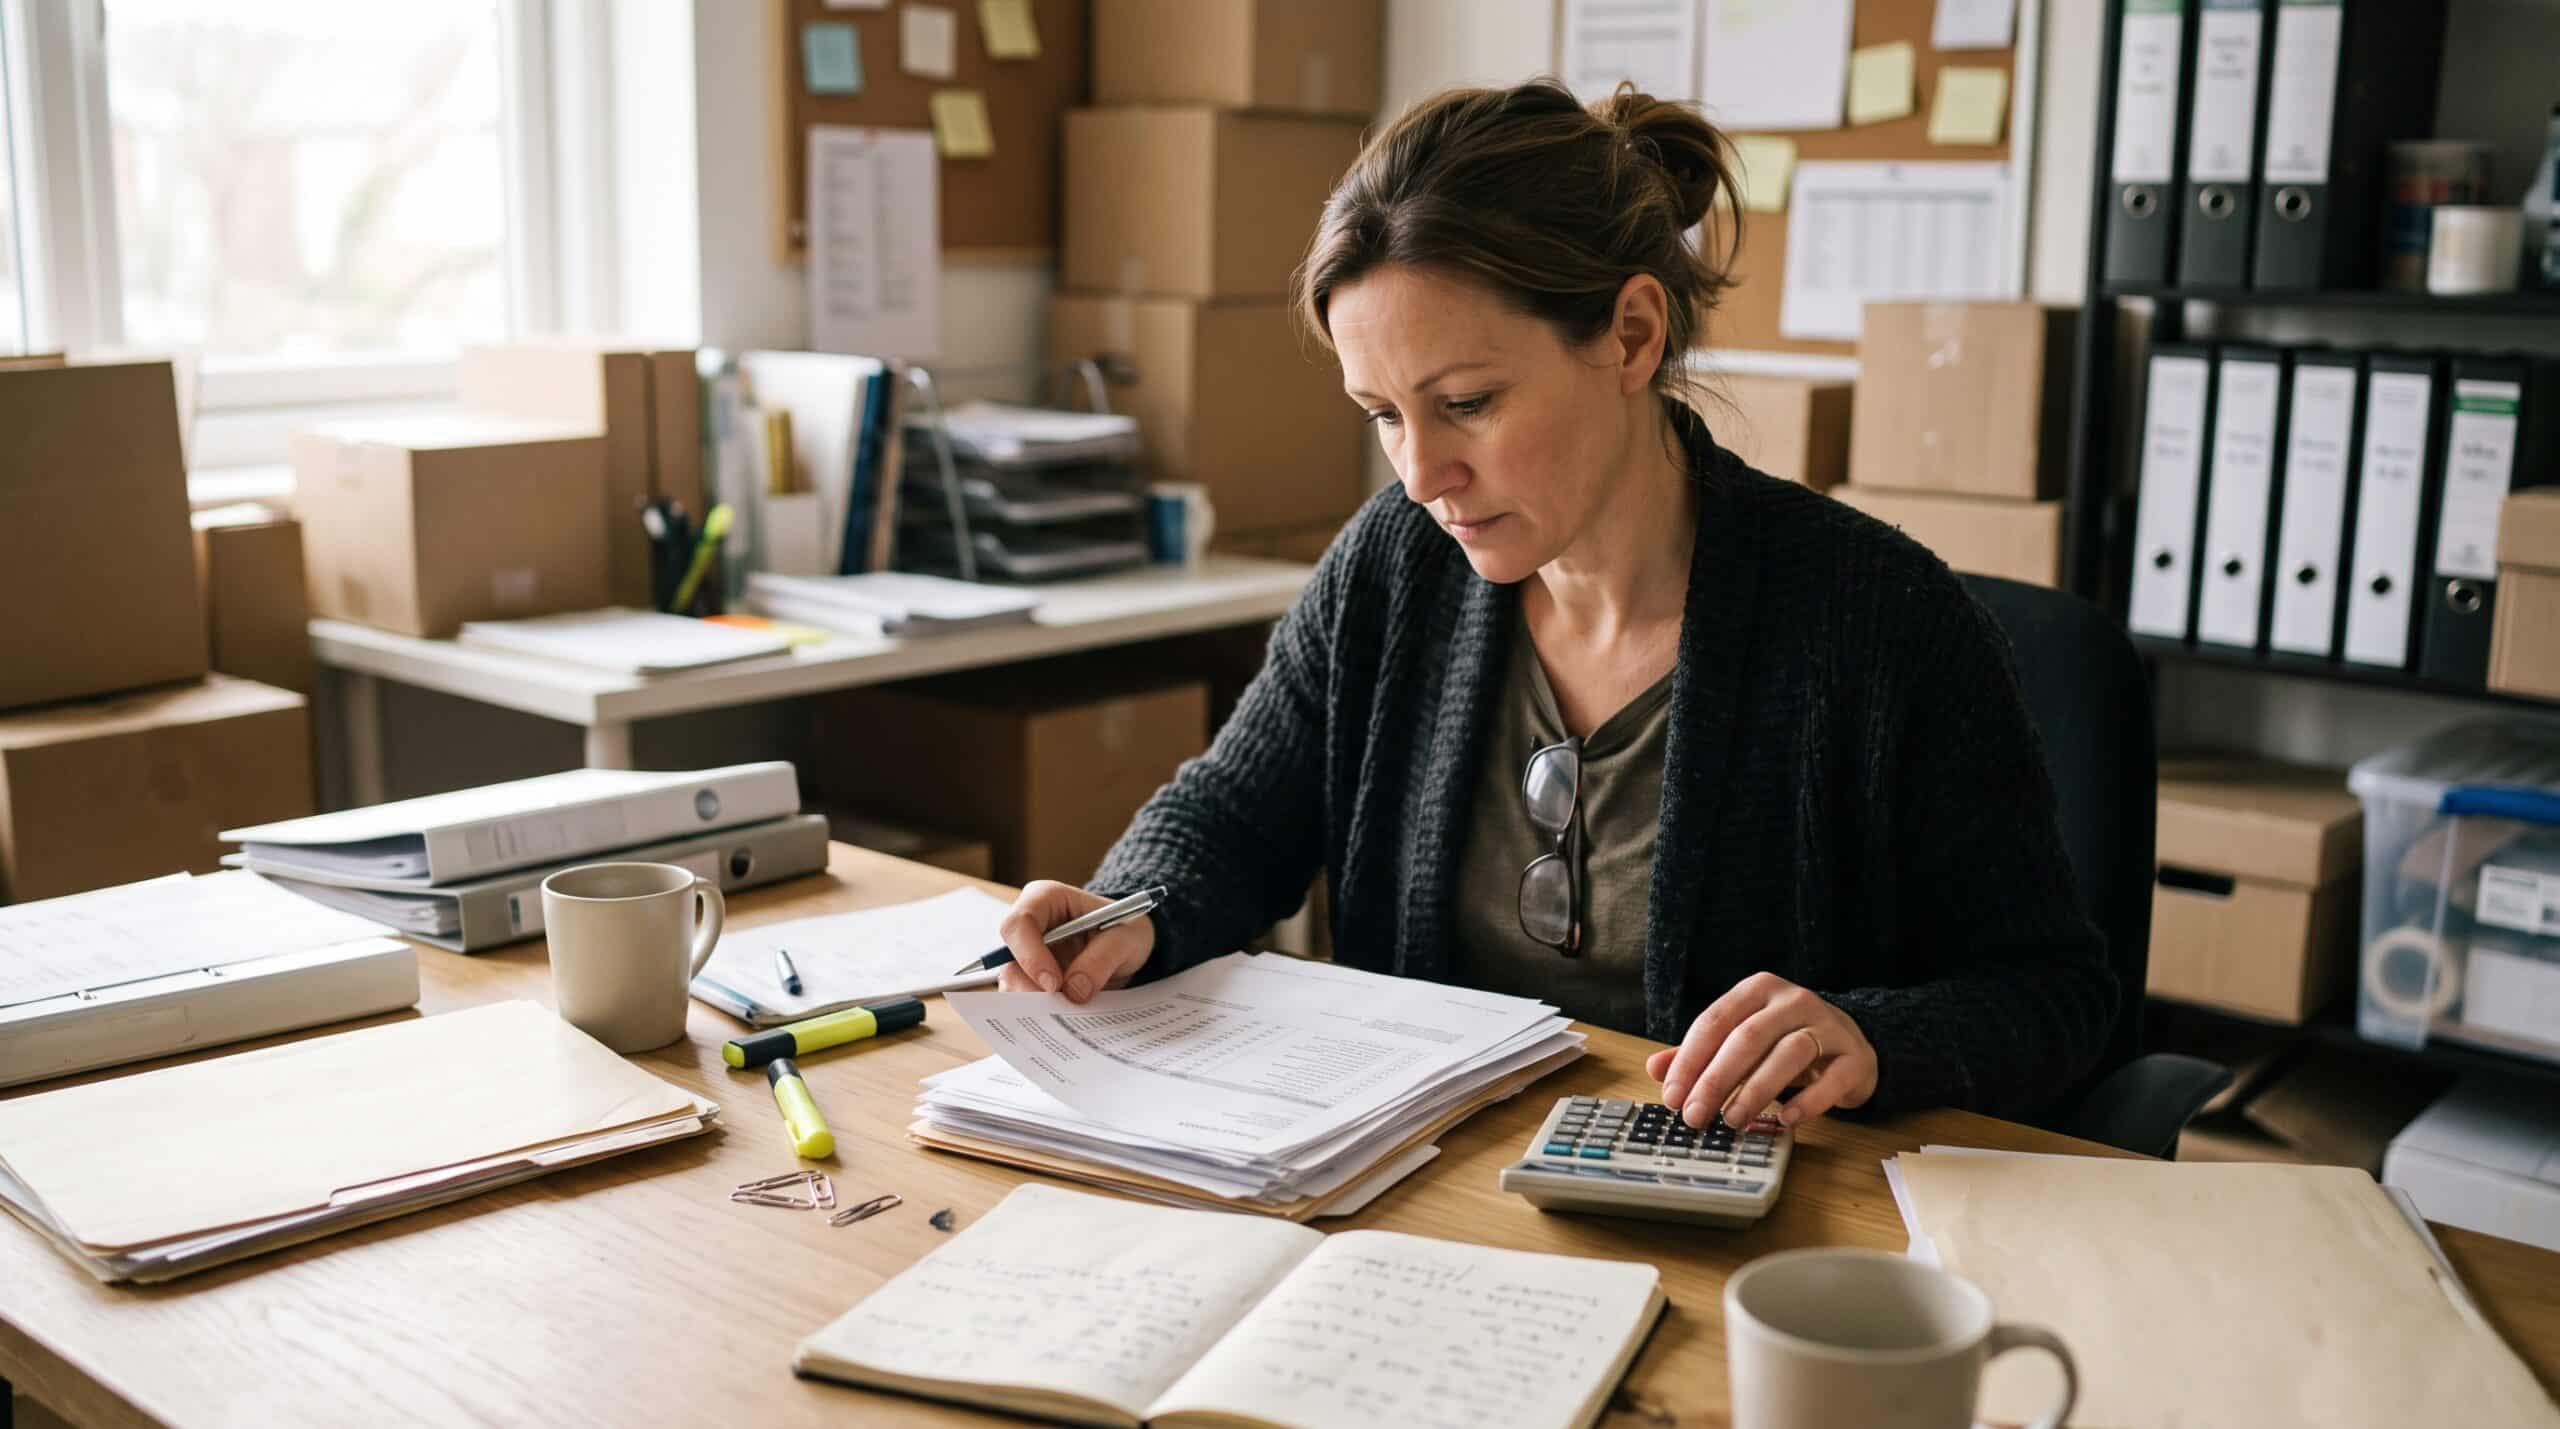
Rising interest rates punish optimistic cash forecasts. Build a thirteen-week cash view. Separate must-pay items from flexible spend. Invoice faster, follow up sooner, and offer small early-pay incentives only when the math beats the cost of borrowing. Owners who know their cash runway sleep better—and negotiate better.
Price adjustments may be necessary where contracts allow and markets tolerate. Communicate value clearly; customers facing their own higher costs scrutinize every increase. Pair price with reliability, speed, or bundled service so the change is not only a number on a page.
FAQ
How do rising interest rates affect small business loans?
Variable-rate loans and new fixed-rate loans generally become more expensive, increasing monthly debt service and the hurdle rate for financed projects.
Will my existing fixed-rate loan increase?
Typically not until refinance, maturity, or a contractual adjustment. Read your note for rate-reset language.
Why is my credit card or line rate up if I did nothing?
Many consumer and business lines reprice with benchmark rates set by lenders responding to policy rates and risk.
Should I pay down debt or keep cash?
It depends on rate levels, prepayment penalties, and liquidity needs. Run scenarios with an accountant or trusted advisor.
Are higher rates always bad for every small business?
Some savers earn more on cash balances, and well-capitalized firms can gain share when leveraged rivals pull back. Most debt-dependent operators feel net pressure.
Is this financial advice?
No. It is general education. Consult your lender, accountant, or financial advisor for decisions about your business.
Run the Business Like Credit Is Scarce—Because It Is Pricier
Rising interest rates affect small businesses through costlier debt, more cautious customers, stricter underwriting, and a higher bar for expansion. You cannot control the central bank. You can control visibility into your loans, the speed of your collections, the lean-ness of inventory, and the honesty of your growth math.
This month, list every credit facility with rate type and reset date, build or update a short-term cash forecast, and identify one financed purchase you can delay or fund differently. Higher rates reward operators who treat cash like a product and debt like a tool with a sharp edge—useful when handled carefully, expensive when left unexamined.
Leave a Reply